DID YOU KNOW... that in 2024 & 2025, the City of Victor improperly moved hundreds of thousands of dollars from its Water & Sewer Enterprise Funds to its General Fund?
When recently reviewing the City’s audited financial statements for 2024 and 2025, VVC discovered that the City of Victor is moving the interest earned on residents' sewer and water fees to the general fund. For example, in 2024, as shown below in Figure #2, the Victor Wastewater Fund earned interest of $143,320 at 4,49%. But instead of all or most of this interest being deposited back into the Wastewater Fund, it was moved in full to the General Fund. Similarly, the Victor Water Fund earned $114,627 of interest in 2024, all of which was again moved to the General Fund. So in 2024 alone, $257,947 of interest earned in the City’s Water & Wastewater Funds was transferred to the General Fund—with no public explanation.
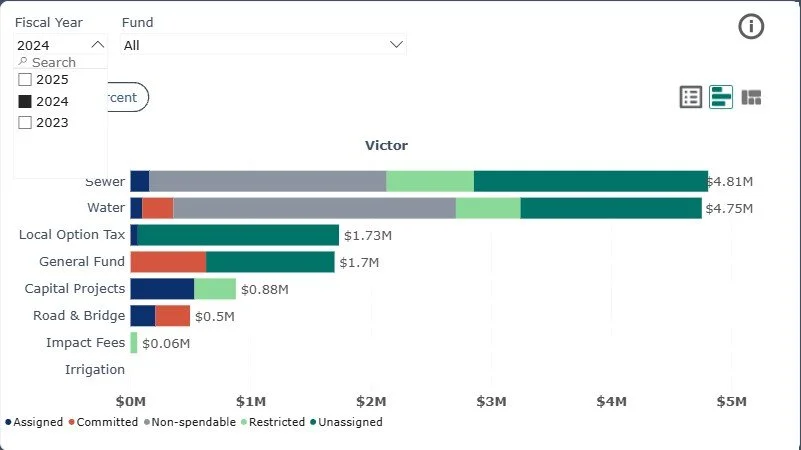
In 2025, once again ALL of the interest earned from the City's Water Fund, $68,516, was moved to other funds (see Figure #1, below). While cities in Idaho are granted broad discretion to sweep interest income into the General Fund, there are explicit exceptions to this practice for Enterprise Funds, and for ‘restricted’ portions of funds. As shown below in Figures #3 and #4, which are taken directly from the Idaho Government Transparency Page, that provides an interactive public portal into Victor’s reported financial data, significant portions of both Victor’s Water and Wastewater Funds are clearly designated as ‘restricted.’ Thus, sweeping all interest earned from these restricted funds into the city's unrestricted general fund appears improper and possibly illegal. All fees paid into an enterprise fund must be used only for the specific purpose of that fund (in this case, water and sewer services), and so moving restricted enterprise funds into the general fund would likely be considered an illegal tax.
To review and/or download the City of Victor’s audited financial statements , CLICK HERE:
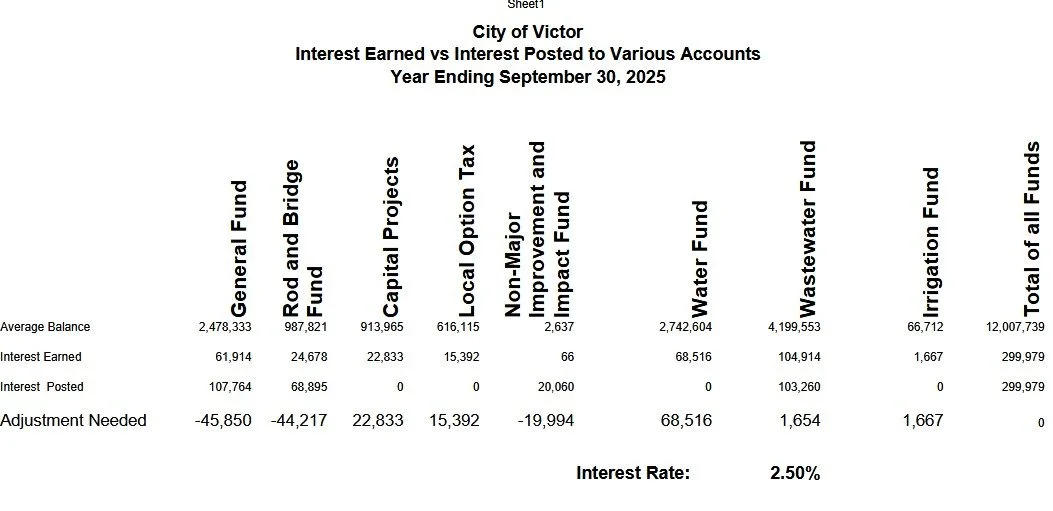
FIGURE #1
FIGURE #3
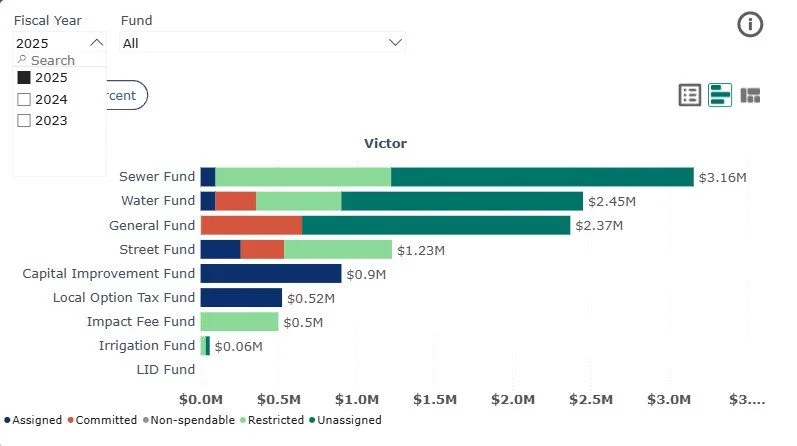
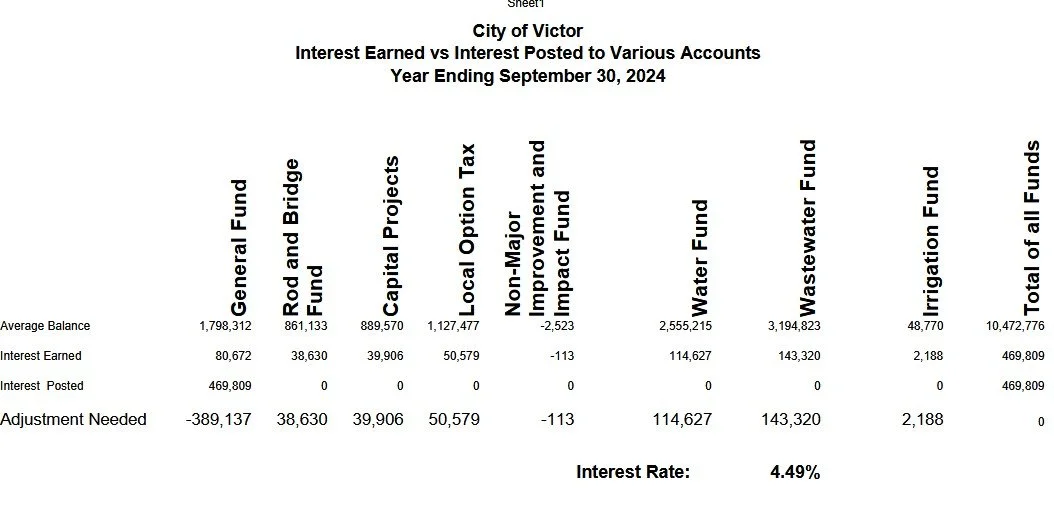
FIGURE #2
FIGURE #4